Financing Structure Q3 2026
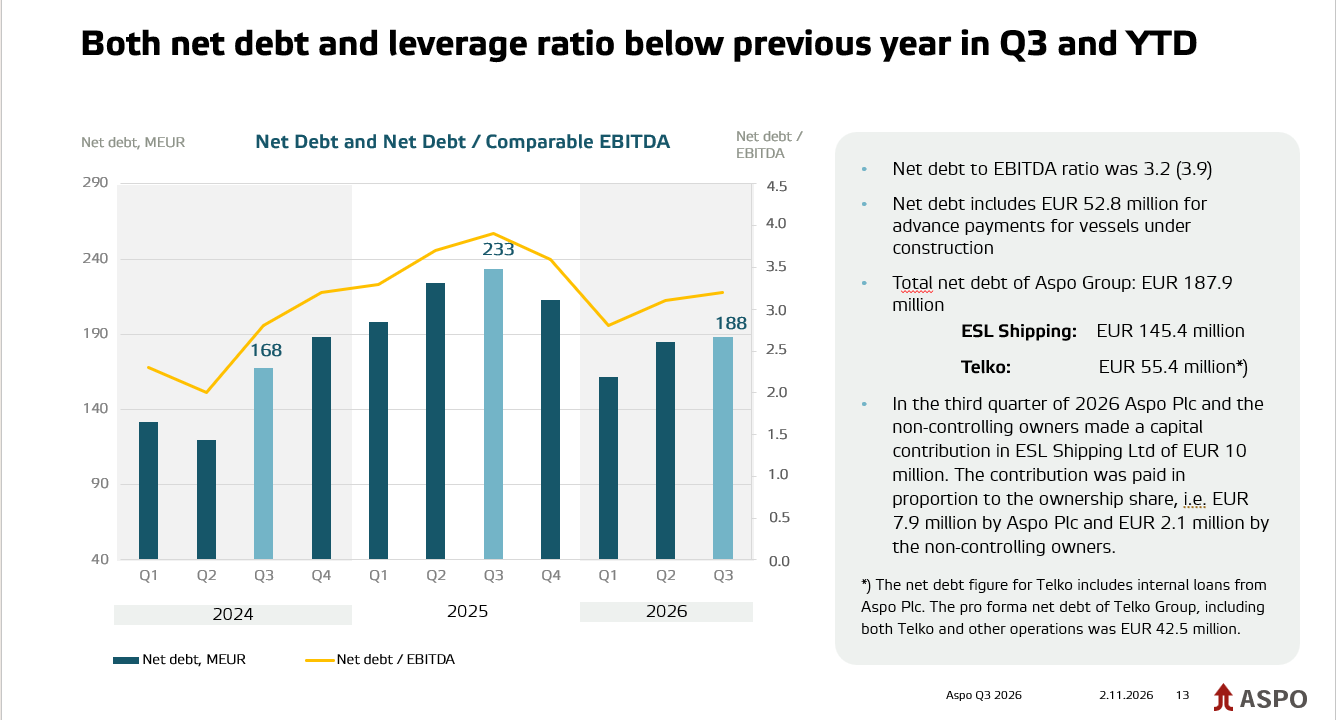
Net interest-bearing debt was EUR 187.9 (12/2025: 212.8) million, and the net debt to comparable EBITDA, rolling 12 months ratio was 3.2 (3.9). The net debt includes EUR 52.8 million for financing the advance payments of vessels under construction. The Group’s equity ratio at the end of the review period was 40.1% (12/2025: 31.9%). The decrease in net interest-bearing debt was mainly caused by the divestment of Leipurin. The net cash inflow from the divestment of Leipurin was EUR 58.1 million, and the reduction in lease liabilities was EUR 4.9 million. The enterprise value (EV) of the transaction was EUR 63 million. Also, the equity ratio increased due to the divestment of Leipurin.
Net financial income in January–September totaled EUR 0.7 (-4.8) million. The reason for the net being a positive amount is that an additional purchase price relating to an acquisition done in previous years was realized at a lower value than estimated and created a financial income of EUR 6.5 (3.2) million in the second quarter of 2026. The average interest rate of interest-bearing liabilities, excluding lease liabilities, was 4.4% in September 2026 compared to 4.1% in September 2025.
The Group’s cash and cash equivalents stood at EUR 26.2 million at the end of the review period (12/2025: EUR 44.0 million including the cash and cash equivalents of the discontinued operation classified as held for sale). Committed revolving credit facilities, totaling EUR 45 (40) million, were fully unused, as in the comparative period. The revolving credit facilities are maturing in 2027-2031. Aspo’s EUR 80 million commercial paper program was also fully unused.
In the third quarter of 2026, Aspo Plc and the non-controlling owners made a capital contribution in ESL Shipping Ltd of EUR 10 million. The contribution was paid in proportion to the ownership share, i.e. EUR 7.9 million by Aspo Plc and EUR 2.1 million by the non-controlling owners. This improved the total equity of Aspo by EUR 2.1 million. The payment done by the non-controlling owners is presented in the financing cash flow.
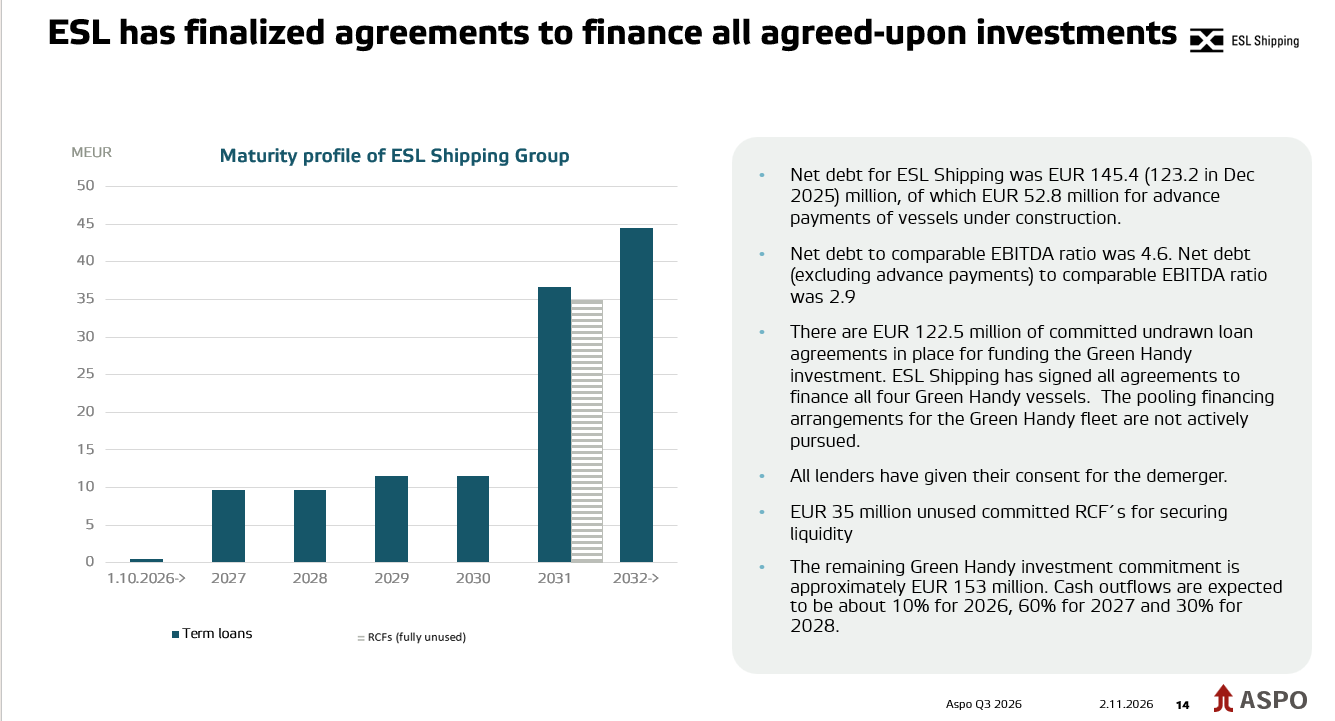
During the third quarter ESL Shipping Ltd entered into a EUR 30 million term loan agreement and agreed on a EUR 15 million revolving credit facility with Danske Bank. Hence, ESL Shipping has signed all agreements to finance the investments in the next generation vessels through committed financing arrangements and credit commitments. The pooling financing arrangements for the Green Handy fleet are currently not actively pursued.
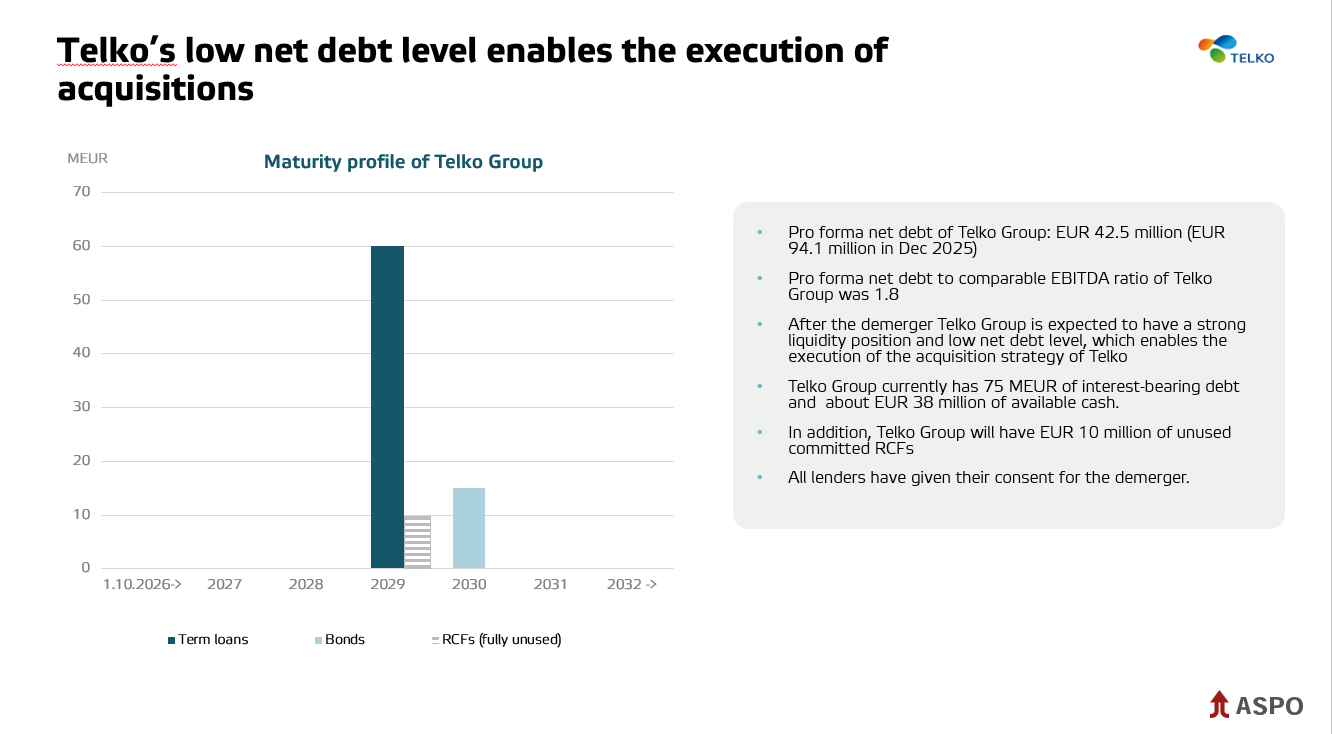
In the possible demerger all the loans of Aspo Plc would continue as loans for Telko Group and all the loans of ESL Shipping Ltd and its subsidiaries would continue as loans of ESL Shipping Group. All the lenders have given their consent for the demerger.
Based on a pro forma balance sheet of September 30, 2026, the net debt of Telko Group would be EUR 42.5 million and ESL Shipping Group EUR 145.4 million. The loan maturity schedule is presented in the Financial information section.